

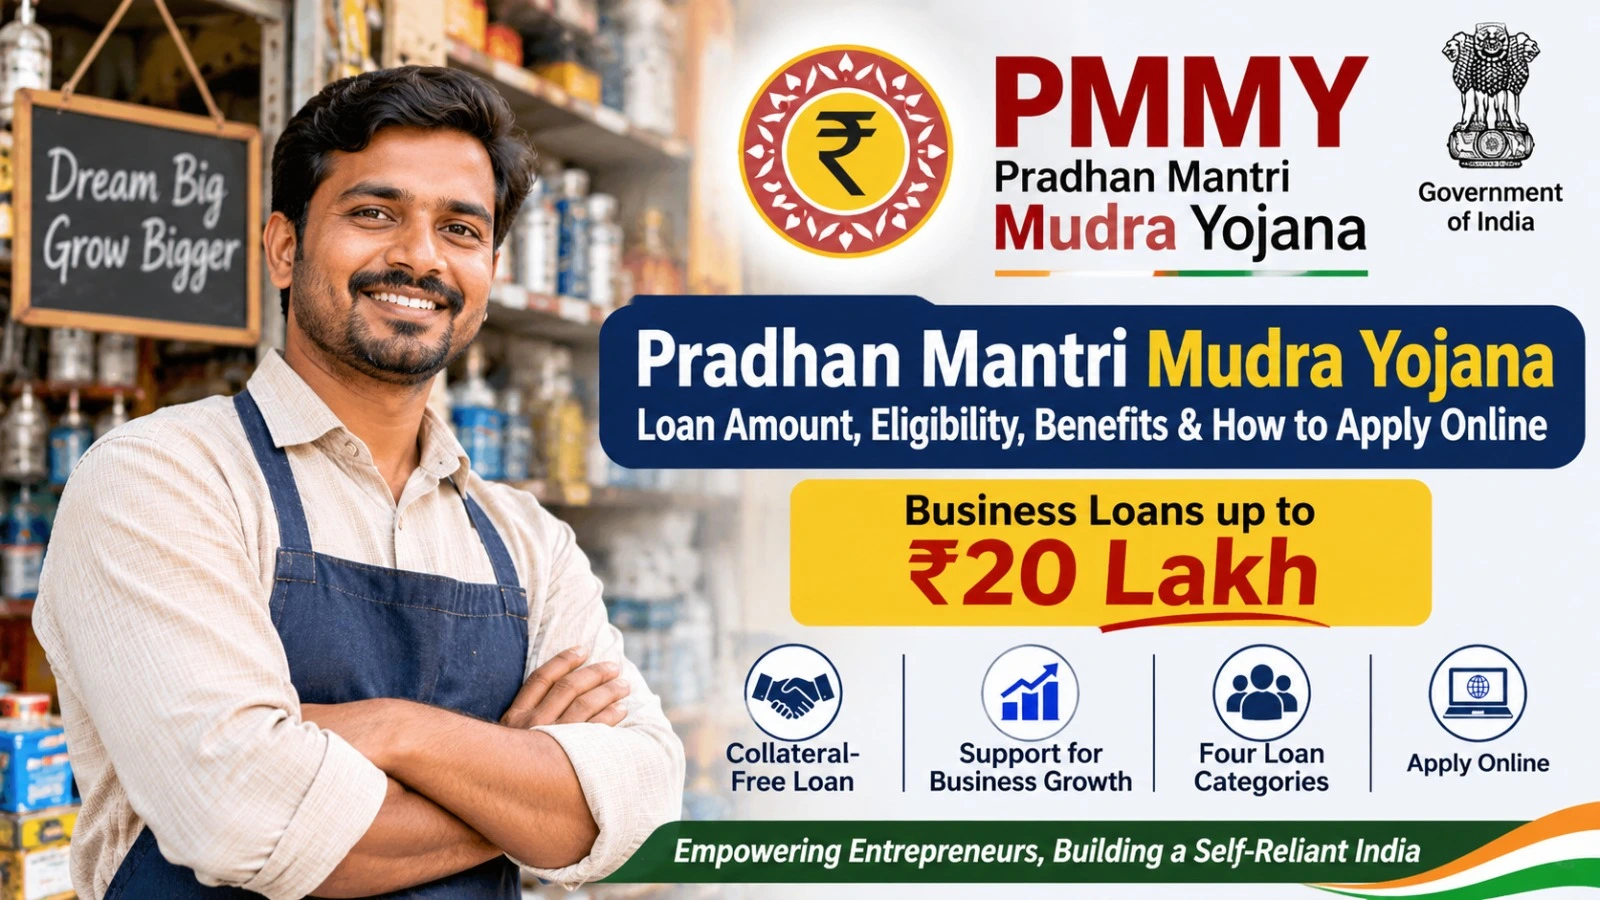
Starting a small business requires proper financial planning, but arranging funds can be difficult for many aspiring entrepreneurs. To improve access to business finance, the Government of India introduced the Pradhan Mantri Mudra Yojana (PMMY). The scheme supports eligible micro and small business owners by providing collateral-free institutional loans through participating financial institutions.
Under PMMY, eligible applicants can access business loans of up to ₹20 lakh under four categories: Shishu, Kishor, Tarun and Tarun Plus. These categories cover different stages of business development, from starting a small enterprise to expanding an existing business.
What Is Pradhan Mantri Mudra Yojana (PMMY)?
Pradhan Mantri Mudra Yojana was launched on 8 April 2015 to provide financial support to micro and small businesses involved in income-generating activities.
The scheme covers eligible businesses in manufacturing, trading, services and certain agriculture-allied activities. Applicants can seek financial assistance for business-related investments and working capital requirements.
PMMY loans are provided through participating banks, Non-Banking Financial Companies (NBFCs) and Microfinance Institutions (MFIs). The loan approval decision depends on the applicant’s business proposal and the lender’s assessment.
PMMY Loan Amount and Categories
The scheme offers four loan categories according to the financial requirements of the business.
| Loan Category | Loan Amount |
| Shishu | Up to ₹50,000 |
| Kishor | Above ₹50,000 to ₹5 lakh |
| Tarun | Above ₹5 lakh to ₹10 lakh |
| Tarun Plus | Above ₹10 lakh to ₹20 lakh |
Important: Tarun Plus is available to entrepreneurs who have previously availed and successfully repaid a Tarun-category loan. The increased loan limit of ₹20 lakh became effective from 24 October 2024.
PMMY Loan Eligibility Criteria
Individuals planning to establish or expand an eligible micro-business can apply for a Mudra loan, subject to the lending institution’s requirements.
Potential applicants include:
- Small shopkeepers and retailers.
- New entrepreneurs starting a business.
- Small manufacturing units.
- Service-sector business owners.
- Artisans and repair-service providers.
- Eligible agriculture-allied businesses, including dairy and poultry activities.
Applicants should have a genuine business requirement and the ability to repay the proposed loan. The financial institution evaluates the application before approving the loan.
Benefits of Pradhan Mantri Mudra Yojana
PMMY offers several benefits to eligible small business owners:
Collateral-free credit: Eligible borrowers can access institutional business credit without providing separate collateral security.
Multiple loan categories: Four categories help applicants identify a suitable financing range according to their business requirements.
Support for business expansion: Existing enterprises can seek financial assistance for eligible business activities.
Working capital support: Approved financing may be used for business working capital and other permitted requirements.
Access through multiple institutions: Applicants can approach participating banks, NBFCs and MFIs.
Documents Required for PMMY Loan
The documents required may vary depending on the lender, loan amount and business activity. Generally, applicants may need:
- Aadhaar card or accepted identity proof.
- PAN card, where applicable.
- Address proof.
- Recent passport-size photographs.
- Bank account details and statements.
- Business address or registration details, if applicable.
- Business plan or project report.
- Equipment quotations or financial estimates, where required.
Applicants should confirm the latest document requirements with their selected financial institution.
How to Apply for a PMMY Loan Online?
Applicants can explore the available online application facility through the JanSamarth portal.
Follow these steps:
Step 1: Visit the official website: https://www.jansamarth.in/
Step 2: Explore the available business loan schemes and check the applicable eligibility requirements.
Step 3: Enter the requested personal, business and financial information.
Step 4: Submit the required documents and supporting details.
Step 5: Follow the portal instructions to proceed with a participating lending institution.
Step 6: The lender will assess your application, business requirements and repayment capacity.
Step 7: If approved, the loan will be processed and disbursed according to the lender’s terms.
Online submission does not guarantee loan approval.
PMMY Interest Rate and Repayment Period
There is no single fixed interest rate for all PMMY loans. The applicable interest rate, repayment period, instalments and charges depend on the lending institution and the borrower’s loan agreement.
Applicants should compare available loan terms and review the Key Facts Statement (KFS) before accepting an offer.
Official PMMY Website and Application Links
| Purpose | Official Website |
| MUDRA Official Website | https://www.mudra.org.in/ |
| Online Application Portal | https://www.jansamarth.in/ |
| Department of Financial Services | https://financialservices.gov.in/ |
Frequently Asked Questions
What is the maximum loan amount under PMMY?
Eligible borrowers can receive up to ₹20 lakh under the Tarun Plus category, subject to its eligibility conditions.
Can new entrepreneurs apply for a Mudra loan?
Yes. Eligible individuals planning to establish a new micro-business can apply, subject to lender approval.
Is collateral required for PMMY loans?
PMMY provides collateral-free institutional credit, although primary security over assets created from the loan may apply.
Where can I apply for a Mudra loan?
You can explore the JanSamarth portal or contact a participating bank, NBFC or MFI.
Conclusion
The Pradhan Mantri Mudra Yojana provides an opportunity for eligible entrepreneurs to access institutional finance for starting or expanding small businesses. Understanding the loan categories, eligibility conditions and application process can help applicants choose the appropriate financing option. Before applying, review the latest scheme guidelines and loan terms through official government sources.